A $1 million home in San Diego at today's roughly 6.95% rate, with 20% down, runs close to $6,300 to $6,700 a month once you add property tax, insurance, and any HOA or Mello-Roos on top of principal and interest. The mortgage itself is only part of that number. On a $1 million purchase, principal and interest alone lands around $5,300 a month; the rest comes from the pieces buyers routinely underestimate. Below is the real breakdown at three price points, plus a calculator so you can plug in your own numbers instead of taking our word for it.
The monthly number at three price points
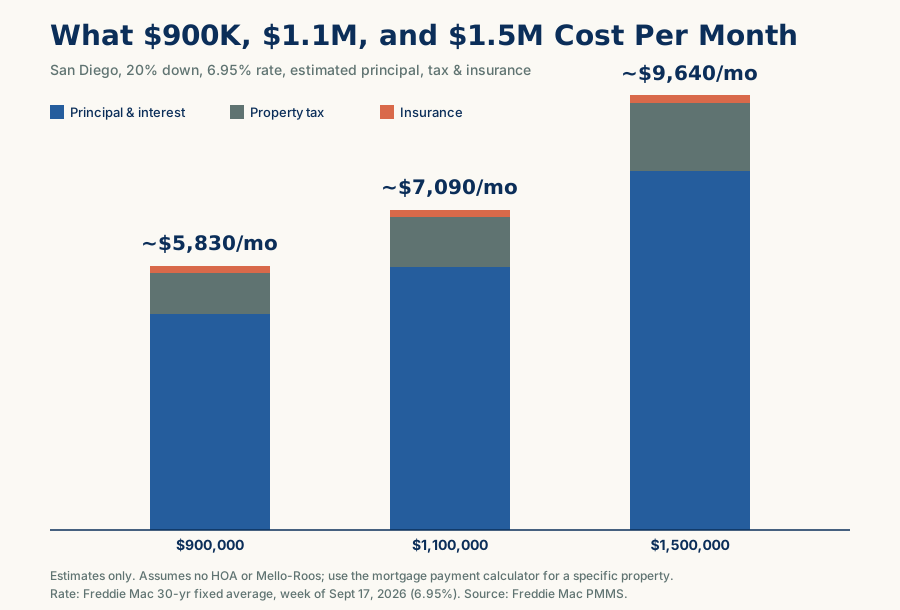
These figures assume 20% down, a 30-year fixed loan at 6.95% (Freddie Mac's published average for the week of September 17), California's blended property tax rate of roughly 1% to 1.25%, and a mid-range insurance estimate. No HOA or Mello-Roos is included here since those vary block by block; add them in the calculator below for a specific property.
| Home price | Loan amount (80%) | Principal & interest | Property tax (est.) | Insurance (est.) | Estimated total |
|---|---|---|---|---|---|
| $900,000 | $720,000 | ~$4,780 | ~$900 | ~$150 | ~$5,830 |
| $1,100,000 | $880,000 | ~$5,840 | ~$1,100 | ~$150 | ~$7,090 |
| $1,500,000 | $1,200,000 | ~$7,965 | ~$1,500 | ~$175 | ~$9,640 |
Two things move these numbers more than anything else: your down payment percentage and your actual rate, which depends on credit, loan type, and points. Add even 5% more down and the $1.1M payment drops by several hundred dollars a month; a quarter-point rate change moves it by a similar amount in the other direction.
Use the calculator for your specific numbers
The table above is a starting point, not your number. Property tax rates, HOA dues, and especially Mello-Roos assessments vary enormously by neighborhood and even by specific development. Plug in a real price, your expected down payment, and the HOA or Mello-Roos figure from an actual listing to see your estimated payment.
What Would This Home Actually Cost You Per Month?
Principal, interest, taxes, insurance, HOA, and Mello-Roos: the real number, not just the sticker price.
$6,446/month, estimated
- Principal & interest
- $5,296
- Property tax
- $1,000
- Mello-Roos / CFD
- $0
- Homeowners insurance
- $150
- HOA
- $0
- Loan amount
- $800,000
Estimate only. Assumes a standard fixed-rate loan with no mortgage insurance and does not include a specific lender quote, PMI, or closing costs. Property tax uses California's roughly 1% to 1.25% blended base rate plus voter-approved assessments; actual Mello-Roos and special-assessment amounts vary block by block and should be confirmed against the specific property's tax bill. Rates move daily, so confirm today's rate and your personal quote with a licensed loan officer before treating any number here as final.
Get a payment plan built around your target areasWhere the "extra" costs actually come from
Property tax. California's base rate is roughly 1% of assessed value, but most San Diego bills run closer to 1.1% to 1.25% once voter-approved bonds and assessments are layered in.
Mello-Roos. This is the one that catches buyers off guard. It is a special tax district, not a base rate, used to fund roads, schools, and infrastructure in newer communities such as parts of 4S Ranch, San Elijo Hills, and Otay Ranch. Older, already-built-out neighborhoods like North Park or Kensington typically have none. Always pull the actual Mello-Roos figure from the property's tax bill rather than assuming.
HOA dues. Detached single-family homes outside a planned community often have no HOA at all. Attached homes, townhomes, and anything in a master-planned neighborhood almost always do, and dues can range from under $100 a month to several hundred for developments with shared amenities.
Insurance. California homeowners insurance has gotten more expensive and, in some fire-adjacent areas, harder to place at all. Get a specific quote before assuming the mid-range estimate above applies to a particular property.
The rate context behind this math
The Federal Reserve raised its benchmark rate a quarter point on September 16, its first increase since 2023, and mortgage rates moved up in response. Freddie Mac's weekly survey put the 30-year fixed average at 6.95% for the week of September 17, a 19-month high, while several lenders' daily averages were already running into the low 7% range. That is the backdrop for the numbers above, and it is also exactly why the calculator matters more than a static table: rates move week to week, and your actual quote will depend on your credit profile and the day you lock.
Frequently asked questions
What income do you need to buy a $1 million home in San Diego?
Most lenders want housing costs at or under roughly 36% to 43% of gross monthly income. On a $1 million purchase with 20% down at today's rate, that generally points to household income in the mid-$200,000s or higher, though the exact figure depends on debt, credit, and loan program.
Is $1 million enough to buy a house in San Diego right now?
Yes in many neighborhoods, though not all. San Diego County's median detached-home price was running close to $1.09 million as of August, so $1 million buys at or slightly below the county median, with more options in inland and value-oriented areas than along the immediate coast.
What is Mello-Roos, and does it apply to every San Diego home?
It is a special assessment, separate from base property tax, used to fund infrastructure in newer master-planned communities. It does not apply to every home. Older, established neighborhoods often have none, while newer developments can add a meaningful monthly amount, so always check the specific property's tax bill.
Does a bigger down payment always beat a lower rate?
Not necessarily. Both reduce the payment, but which matters more depends on the size of the change. A meaningful rate reduction on a large loan can outweigh a modest increase in down payment, so it is worth modeling both instead of assuming one lever is stronger.
Should I wait for rates to drop before running these numbers?
That depends on your own timeline and risk tolerance more than on any prediction we could make here. See the companion buy-now-vs-wait calculator for a side-by-side on that exact question.
What to do with this number
Once you know your realistic monthly payment, the next useful step is matching it to actual San Diego neighborhoods and listings rather than a hypothetical price. Get your home value, or a custom San Diego search built around this payment range, and we can narrow it down together.